
In a seismic shift that has redrawn the map of global energy geopolitics, the United States has officially ascended to the position of the world’s largest crude oil exporter. Data confirmed in 2026 reveals that the American energy sector has moved beyond mere self-sufficiency, becoming the primary engine fueling markets across Europe, Asia, and Latin America. This transition marks the end of an era defined by reliance on the Middle East, signaling a profound reconfiguration of global trade routes and economic influence.
The Ascent to Energy Dominance: Main Facts
The rise of the U.S. as a global energy hegemon is not an overnight phenomenon but the culmination of years of aggressive domestic production and strategic infrastructure development. By mid-2026, U.S. crude exports were consistently exceeding 4 million barrels per day (BPD), effectively outpacing the export volumes of traditional giants like Saudi Arabia and Russia.
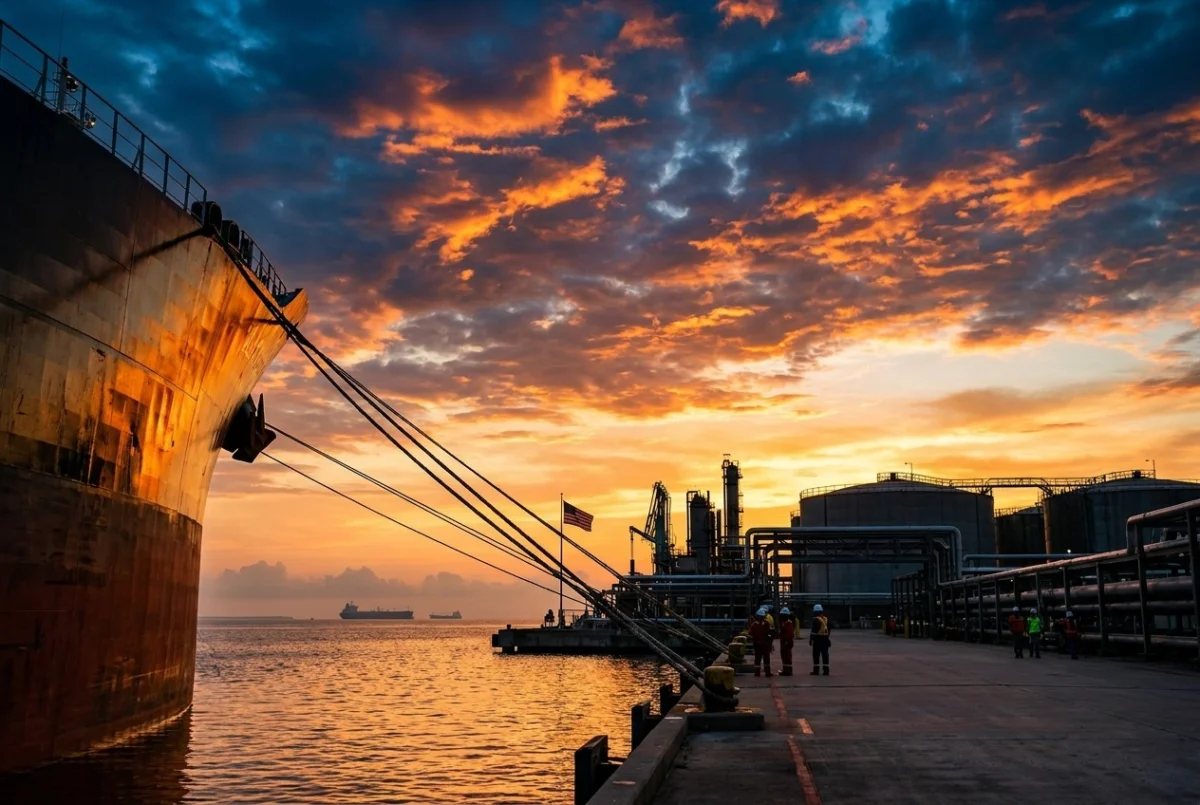
The foundation for this success was laid by the relentless productivity of the Permian Basin and significant investments in Gulf Coast export terminals. These facilities have transformed the American coastline into the world’s most critical energy gateway, allowing U.S. crude to bypass traditional bottlenecked shipping lanes and reach eager buyers in the Atlantic and Pacific basins.
A Chronology of the Shale Revolution
The trajectory of the American energy sector is a story of technological triumph and policy pivoting.
- The Early Years (2010–2020): The "North American Shale Revolution" utilized hydraulic fracturing and horizontal drilling to unlock vast reserves previously deemed inaccessible. This period saw production climb to three-decade peaks, fundamentally changing the domestic energy landscape.
- The Transition (2021–2024): Despite initial political debates regarding environmental policies and industry regulation, the momentum of the private sector remained robust. Infrastructure projects initiated years prior began to come online, expanding the capacity to transport crude from landlocked basins to deep-water ports.
- The Surge (2025): The Energy Information Administration (EIA) confirmed that the U.S. became the world’s largest producer in 2025, hitting a record 13.6 million BPD.
- The Export Era (2026): By 2026, the focus shifted from pure production to export dominance. As geopolitical instability shuttered traditional supply routes in the Middle East, the U.S. stepped in to fill the void, solidifying its role as the world’s "swing supplier."
Supporting Data: The Numbers Behind the Power
The sheer scale of U.S. production has created a widening gap between the United States and its closest competitors. According to the July 9, 2025, report from the EIA, the U.S. output of 13.6 million BPD stood significantly higher than Russia’s 9.9 million BPD and Saudi Arabia’s 9.6 million BPD.
Projections for the remainder of 2026 are even more ambitious. The EIA indicated on September 10 that total U.S. production is expected to reach an all-time high of 13.8 million BPD by year-end. This growth is bolstered by four major new production projects nearing completion.
The stability of this supply is crucial. While other nations have faced production declines due to political unrest, sanctions, or aging infrastructure, the U.S. has leveraged its advanced shale extraction technologies to maintain a consistent upward trajectory. As analyst Aaron Day noted, the U.S. remains on the "cutting edge" of shale oil technology, a position that has allowed the nation to maintain high output even when market conditions were unfavorable for other global players.
Global Market Effects: Navigating Instability
The rise of U.S. energy dominance has been tested by severe geopolitical volatility. The recent closure of the Strait of Hormuz—which typically handles 20% of the world’s oil—sent shockwaves through global markets. When Iranian forces effectively blocked the passage amid ongoing tensions with Israel and the United States, crude prices spiked by nearly 50%, with gasoline costs in the U.S. briefly breaching the $4-per-gallon mark.
However, the catastrophic market collapse that many analysts feared did not materialize. The resilience of the global market was largely attributed to two factors: the strategic stockpiles maintained by China and the sheer volume of U.S. crude currently circulating in the global market. The ability of U.S. producers to ramp up supply from Gulf Coast terminals acted as a critical stabilizer, preventing a prolonged energy crisis.
Official Responses and Geopolitical Maneuvering
The shift in power has not gone unnoticed by the Organization of the Petroleum Exporting Countries (OPEC). Officials have publicly stated that they are "closely monitoring" U.S. export growth, with an eye toward maintaining market stability. Saudi Arabia, historically the world’s most influential oil player, has responded by cutting its own production, a move that signals a departure from its traditional role as the world’s price setter.
Within the United States, the response has been polarized. Proponents of the current energy policy, particularly within the Trump administration, emphasize the importance of "energy dominance" as a pillar of national security. By deregulating the industry and encouraging rapid exploration, the administration has successfully reversed earlier production constraints. Furthermore, the government has looked beyond domestic shale, securing a landmark deal with Venezuela that grants the U.S. access to, and majority control over, more than 65 billion barrels of proven reserves.
Conversely, critics in Congress have raised significant concerns regarding the environmental impact of this surge in production. The tension between achieving energy independence and meeting climate commitments remains a central, unresolved debate in American politics.
Implications for the Future
As we look toward 2027 and beyond, the energy landscape remains fluid. The future of U.S. exports will depend on three key variables: global demand, the cost of extraction in the Permian Basin, and the continued expansion of export infrastructure.
- Technological Superiority: While the U.S. has struggled to scale nuclear energy, its dominance in fossil fuel extraction technology—specifically shale—has become its primary exportable commodity. The U.S. is not just exporting oil; it is exporting the methods and machinery of the shale revolution.
- OPEC+ Relations: The relationship between Washington and the OPEC+ cartel is entering a new, delicate phase. As the U.S. assumes the role of the global supplier of last resort, the influence of traditional cartels over global pricing will likely continue to wane.
- The Rebalancing: An energy official recently described the current market as a "historic rebalancing." The Western Hemisphere is systematically replacing the Middle East as the center of gravity for global energy flows.
The shift to American energy dominance is more than just a data point; it is a fundamental realignment of the global economy. By insulating itself from the volatility of the Strait of Hormuz and the political instability of the Eastern Hemisphere, the United States has secured its position as the anchor of the global energy supply chain. Whether this position can be maintained while balancing environmental goals and domestic economic pressures remains the definitive challenge for the coming decade. As the world transitions toward newer energy sources, the U.S. is leveraging its current fossil fuel wealth to dictate the terms of that transition, ensuring that the next chapter of energy history is written largely in American soil.